Cash flow stability is the backbone of the German Mittelstand. Every small and medium-sized enterprise (SME) in Germany works according to a tightly coordinated operational budget that makes the visibility of future revenue an indicator of potential investments, payroll, and credit standing. Nevertheless, in case of a delay in expected payments, even a profitable commercial company experiences operational problems.
Overdue invoices generate friction within corporate accounting by creating the gap between recorded income and available liquidity. Overdue accounts receivables are not just an administrative issue but rather a phenomenon that impacts the entire balance sheet, forcing financial officers to change risk assessment and delay strategic expenditures.
Navigating the complexities of handling overdue business invoices in Germany requires carefully organized financial monitoring, precise legal parameters within the framework of the German Civil Code (Bürgerliches Gesetzbuch or BGB), and comprehensive knowledge of working capital mechanisms. In case of compounding default risks, cash flow planning depends on the cash conversion cycle rather than on income tracking.
The Disruption of Cash-Flow Forecasts
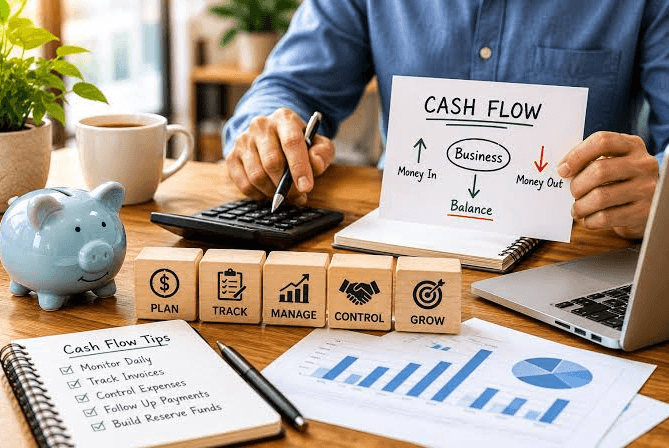
Cash-flow forecasting is highly dependent on predictability. Financial analysts forecast future cash flows according to the established terms of payment (Zahlungsziele) that normally take between 30 and 60 days in Germany. In case of a breach of these terms, the predictability of the company’s financial model is completely ruined. The process of cash-flow forecasting is non-linear; the unforeseen delay of €50,000 from a main client cannot be compensated by delaying general overhead. Fixed payments such as wages, corporate tax, equipment rent, and utility bills need to be paid immediately.
The delay of cash flows creates structural timing problems for SMEs. Financial managers need to take unplanned actions like withdrawing money from short-term reserve accounts or using credit facilities (Kontokorrentkredit) heavily. As stated in the financial reporting guidelines of the Deutsche Bundesbank, high reliance on short-term bank credits to cover the operational gap leads to an increased cost of borrowing, especially in an environment of high-interest rates.
Moreover, cash-flow forecasting distortions affect the supply chain of the company. The SME facing the delay of receivables will delay payments to secondary vendors to preserve liquidity, creating contagion effect in the economy. The Federal Statistical Office of Germany (Destatis) constantly illustrates the consequences of late payments on enterprise liquidity in the industrial and services sectors, proving that late payments affect revenue predictability in regional supply chains.
Erosion of Working Capital and Corporate Liquidity
Working capital is the lifeblood of any business. Calculated as current assets minus current liabilities, it characterizes the enterprise’s short-term solvency and immediate operational capabilities. The presence of overdue accounts receivable artificially inflates current assets, masking the lack of liquidity.
Realignment of Working Capital:
| Accounting Perspective | Operational Reality |
| High Accounts Receivable | Zero Bank Account Growth |
| Reported Profitability | Inability to Fund Inventory |
| Satisfactory Current Ratio | Erosion of Net Cash Position |
As receivables become long overdue debts, the cash conversion cycle (CCC) becomes longer. This makes financing new orders, purchasing raw materials, or investment in capital equipment more difficult. For German SMEs using narrow margin structures, long Days Sales Outstanding (DSO) is a direct threat to business sustainability.
According to the German Civil Code (§ 286 of BGB), a debtor is considered to be in default 30 days after receiving the invoice, if statutory requirements are fulfilled. Moreover, statutory late-payment interest for B2B transactions allows a creditor to charge a rate higher than the Deutsche Bundesbank base rate. Nevertheless, charging statutory interest seldom covers opportunity costs or working capital erosion.
When internal collection procedures stop, effective liquidity management needs professional help. Streamlining debt recovery and handling overdue business invoices in Germany with the help of specialized external recovery services guarantees that enterprises comply with BGB dunning rules and enforce contractual obligations without any disruption of core activities.
See also: How Lyncconf Mods Works: Features, Benefits, and Uses
Receivables Management and Strategic Debt Recovery
Reducing cash-flow distortions presupposes building an effective receivables management system. German SMEs cannot consider credit control just as an administrative procedure; it should be treated as a well-structured financial control procedure. Effective management presupposes early-warning signals, thorough credit evaluation of potential commercial.
Effective management needs to work with proactive early-warning systems, strict credit analysis of possible commercial debtors, and established dunning procedures.
Key elements of a robust receivables strategy include:
- GoBD-Compliant Accounting & Invoicing: Making sure that all the necessary documentation is presented properly, following all the legal standards regarding layouts and deliveries to avoid formal disputes over payments.
- Clear Dunning Schedules (Mahnwesen): Sending reminders (Zahlungserinnerung) in due time after the first deadline and then the actual dunning notices (Mahnung) that set secondary deadlines.
- Decisive External Escalation: Using collection experts’ services or conducting the dunning procedure officially (gerichtliches Mahnverfahren), which will result in the execution order of the debt (Vollstreckungsbescheid).
All official data only confirms the importance of such a well-structured recovery process. Economic statistics that were released in regional corporate payment reports shows that more than 80% of German companies experience overdue payments regularly, with many overdue accounts resulting in increased chances of bankruptcy in the SME segment. By combining internal credit control with decisive recovery workflows, companies can protect their working capital from any liquidity issues.
Strategic Financial Resilience
Overdue invoices mean much more than being a nuisance; they serve as a continuous structural danger to the operational success and growth of the German SME sector. The failure to collect on invoices after the contractual agreement period leads to a reduction in working capital, problems with cash flow planning, and operational costs.
The ability to maintain corporate liquidity is only achieved through proper financial planning, strict compliance with legal dunning limits, and timely implementation of collection methods. By treating receivables management as a fundamental business function, German companies can protect themselves from default risk and ensure liquidity.